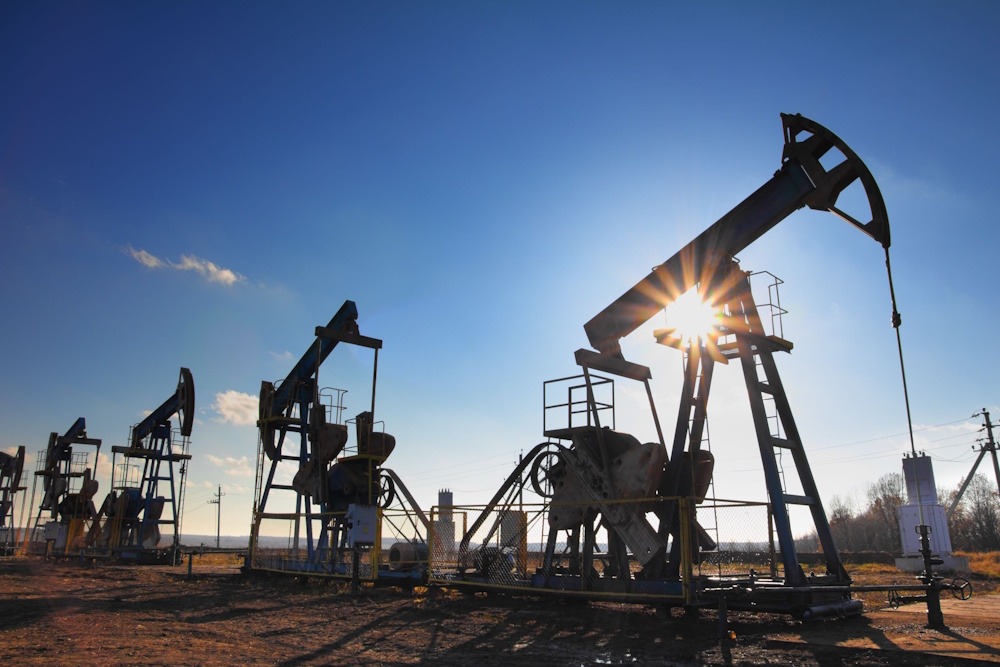
Oil prices experienced an uptick on Friday, October 30, as market participants evaluated the likelihood of the United States reinstating military actions against Iran, which heightened apprehensions regarding regional stability and the potential for disruptions in energy supplies. Brent crude increased to $118, reflecting a 2.5% rise per barrel. US West Texas Intermediate crude gained 2.30% to $104 a barrel. Brent crude has experienced a 12% increase in October, achieving a six-month peak. Despite a recovery in oil flows through the Strait of Hormuz, persistently low inventories and constrained supplies of refined products have maintained upward pressure on prices. The gains followed a report indicating that a senior US military commander had briefed US President Donald Trump on potential military options on Thursday. Trump has consistently suggested the possibility of reinstating airstrikes on Tehran following the midterm elections next week.
Security risks in the Strait of Hormuz have resurfaced following an incident where an unidentified projectile struck a tanker on Thursday as it finished its outbound journey through the waterway, as reported by the UK Maritime Trade Operations. The incident underscored the persistent risk to maritime trade, even as producers have recommenced cargo operations through the strait. Market uncertainty has been exacerbated by the potential for additional Houthi attacks and the prospect of US military intervention in Iran following the elections. The Saudi-led coalition engaged in combat with Yemen’s Houthis reported the successful interception and destruction of a ballistic missile launched by the group targeting Saudi Arabia’s eastern region early on Thursday. Hostilities between the two factions persist, showing scant signs of a potential de-escalation. The Yemeni government forces reported that the Houthis launched an attack on Aden airport on Wednesday.
The incident occurred a day following the group’s assertion of responsibility for a missile strike aimed at Saudi Arabia’s largest oil refinery located at Ras Tanura. These developments indicate a heightened level of aggression directed toward Saudi Arabia, which holds the position of the second-largest crude producer globally, following the United States. Saudi authorities had not yet provided confirmation regarding the reported incident at the refinery, which possesses a capacity of 550,000 barrels per day. The uncertainty surrounding the progression of the conflict persists, obscuring the forecast for oil markets. JPMorgan analysts indicated that evaluating the trajectory of the war continues to pose challenges. At the onset of the conflict, the bank anticipated that the US administration would refrain from surpassing specific economic thresholds.
However, seven months later, several of those limits had been breached, while there remained no clear strategy to bring the conflict to a conclusion. The prospect of additional supply disruptions has bolstered anticipations of elevated oil prices. Daan Struyven stated that recent attacks have illustrated the potential for shipping disruptions to proliferate and escalate. Goldman Sachs has indicated that oil prices may reach $120 a barrel should there be an escalation in attacks on vessels in the Middle East. In contrast, prices may decline to approximately $80 a barrel should exports revert to their normal levels. Struyven indicated that risks to shipping have surfaced as a significant factor influencing oil prices, noting that the bank anticipates substantial upside potential for crude. Goldman Sachs anticipates an uptick in natural gas and refined fuel prices, observing that supply disruptions typically exert a more pronounced effect on gas and refined products compared to crude oil.